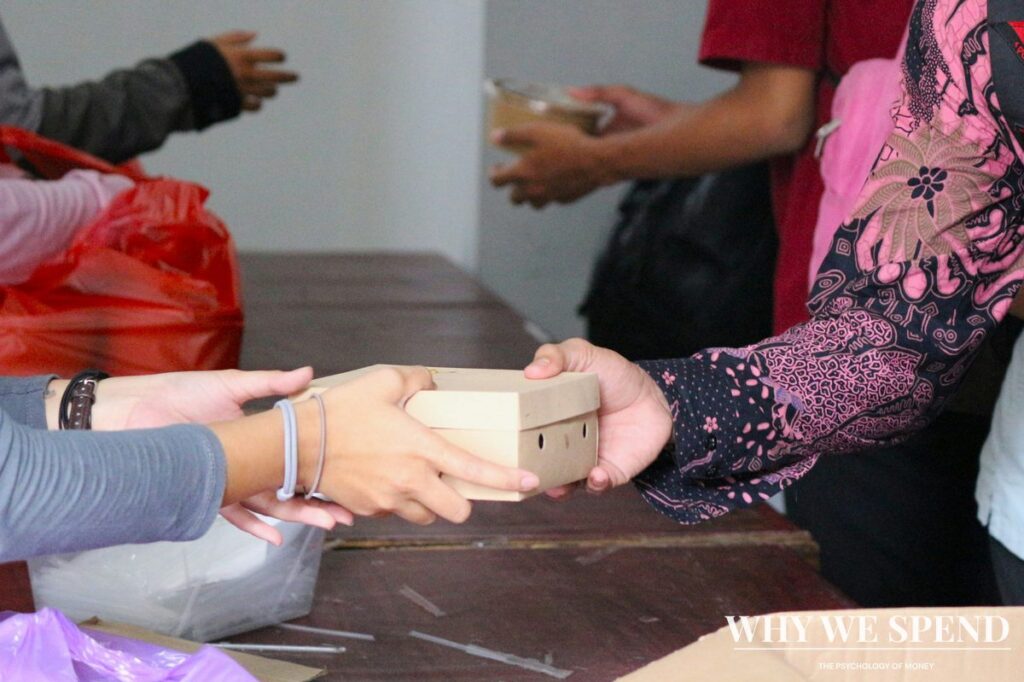
Matched donation psychology reveals something uncomfortable about how people relate to their own money: many of us only feel truly generous when someone else—usually a company or wealthy donor—validates our giving by matching it. The moment a charity announces “Every dollar you give will be matched!” suddenly opens wallets that remained firmly shut just moments before. This isn’t just about getting more impact for the same amount. It’s about needing external permission to part with money, and what that says about personal financial confidence runs deeper than most Singaporeans and Malaysians might realise.
This behaviour shows up everywhere during charity drives. A colleague who wouldn’t donate $20 to a cause suddenly contributes $50 when told it’ll become $100 with matching. The maths makes sense on the surface—double the impact sounds brilliant. But strip away the matching offer, and the original reluctance returns. The cause hasn’t changed. The need hasn’t diminished. Only the external validation has disappeared.
The Psychological Safety Net of Matched Giving
Matched donation psychology operates like a form of financial peer pressure, but the “peer” is an institution with deeper pockets. When DBS or Maybank announces they’ll match donations during a fundraising campaign, something shifts in people’s minds. The act of giving transforms from a solo decision into a collaborative effort. Suddenly, the money feels less “wasted” because someone important has essentially co-signed the decision.
This need for validation extends beyond charity. Consider how Singaporeans and Malaysians approach their Central Provident Fund or Employees Provident Fund contributions. Many view the employer’s portion as the “real” savings whilst treating their own mandatory contribution as a loss of spending power. The employer match validates the savings behaviour, making it feel legitimate. Without that match, voluntary contributions to retirement accounts remain far less common, even when the tax benefits are substantial.
The pattern repeats with credit card rewards and cashback schemes. People will spend an extra RM100 to “unlock” the bank’s matched cashback tier, essentially paying for the privilege of receiving their own money back. The bank’s participation makes the spending feel justified, even smart. Solo spending without that validation? That’s just regular spending, and it doesn’t generate the same dopamine hit.
Why External Validation Feels Necessary
The discomfort with solo generosity often stems from what psychologists call “loss aversion.” Money leaving one’s account registers as a loss, even when it’s funding something meaningful. But when a matching donor steps in, the psychological framing shifts. The loss becomes an investment in a larger transaction. The giver isn’t just losing money—they’re “activating” someone else’s money, which feels productive rather than merely charitable.
For many Singaporeans especially, where kiasu culture runs deep, matched giving also eliminates the fear of being the “only sucker” who contributed. If a major corporation is matching donations, clearly this cause has been vetted and approved by people with financial expertise. The institutional backing serves as social proof that this isn’t money being thrown away.
What Matched Donation Psychology Reveals About Money Confidence
The reliance on matched giving exposes a fundamental lack of confidence in personal financial judgement. When someone needs a corporation to validate their $50 charity donation before they’ll make it, what they’re really saying is: “I don’t trust my own assessment of what’s worth spending money on.”
This manifests in numerous daily spending decisions. Malaysians might hesitate to spend RM80 on a quality kitchen knife that’ll last years, but they’ll instantly buy a RM80 gadget that’s “on sale” from RM120, even if they don’t need it. The discount—another person’s validation that this price is “good”—makes the decision feel safe. The solo decision to invest in quality? That requires confidence many people lack.
The same psychology explains why Singaporeans might refuse to pay $15 for a hawker meal they’ll enjoy but will spend $50 on a mediocre restaurant meal that’s been validated by queues and social media hype. The crowd provides the permission slip to spend. Without it, the money feels too risky to release.
The Corporate Exploitation Factor
Companies understand matched donation psychology intimately, which is why matching schemes remain marketing gold. Banks promote matched giving campaigns not purely from goodwill but because they generate tremendous positive publicity at relatively low cost. They can cap their matching at a predetermined amount whilst reaping unlimited goodwill from appearing generous.
The same principle drives employee benefits. Offering to match staff EPF contributions up to a certain percentage costs employers less than simply paying higher base salaries, but it feels more valuable to employees because of the matching mechanism. The psychological boost from “activating” the match exceeds the practical benefit of the actual money.
Breaking Free from Validation-Dependent Giving
Recognising matched donation psychology in action creates an opportunity to develop stronger financial confidence. The goal isn’t to stop taking advantage of matching offers—they genuinely do amplify impact. Rather, it’s about questioning whether validation-dependent generosity reveals a broader pattern of needing external permission before spending money.
Ask: Would this donation still feel worthwhile without the match? If the answer is no, that’s information worth examining. Perhaps the cause isn’t actually aligned with personal values, and the match was simply providing cover for performative generosity. Or perhaps—more likely—there’s discomfort with trusting personal financial judgement.
The same questioning applies to other spending. That restaurant with a two-hour queue—would the meal still appeal without the social validation? That credit card promotion requiring extra spending to hit the cashback tier—does the maths actually work out favourably, or does the “match” just make wasteful spending feel strategic?
Building Independent Financial Judgement
Developing confidence in solo financial decisions requires practice. Start small: make one unmatched donation to a cause that matters personally, without waiting for a corporate matching campaign. Notice the discomfort. Sit with the feeling that this money is “just” helping others without generating matched funds or tax receipts or public recognition.
Apply the same principle to spending. Buy the quality item without waiting for validation from reviews or sales or queues. Skip the “special promotion” that requires extra spending to unlock rewards. Let some purchases be straightforward transactions based on personal assessment of value rather than external confirmation that the price is “good.”
Lessons: Strengthening Your Money Confidence
Several principles emerge from understanding matched donation psychology:
Principle 1: Validation-seeking reveals confidence gaps. When external approval feels necessary before spending or giving money, that’s a signal to examine whether personal financial judgement needs strengthening. The goal isn’t to ignore useful information from others, but to recognise when outside validation has become a crutch replacing personal discernment.
Principle 2: Matched giving can enable performative generosity. Donations made solely because matching doubled them may reflect more about seeking the feeling of being generous than about genuine commitment to a cause. Real generosity doesn’t need institutional co-signing to feel legitimate.
Principle 3: Solo spending decisions build financial confidence. Each purchase made based on personal assessment of value—without waiting for sales, queues, or corporate promotions to validate the decision—strengthens the ability to trust financial judgement. This confidence compounds over time.
Principle 4: Marketing exploits validation needs. Companies design matching schemes, cashback tiers, and limited-time offers specifically to trigger validation-seeking behaviour. Recognising these mechanisms reduces their power to drive unnecessary spending.
Principle 5: Loss aversion distorts giving behaviour. The discomfort of money leaving an account often has nothing to do with whether someone can afford the donation or whether the cause deserves support. It’s psychological, not financial—and recognising that distinction helps separate genuine resource constraints from fear-based hoarding.
The Path to Financial Autonomy
Matched donation psychology ultimately points to a larger question: Who decides what money is “worth” spending? When that answer consistently comes from external sources—corporations, crowds, discount percentages, matching schemes—personal financial autonomy remains underdeveloped.
The alternative isn’t rejecting all outside information or becoming contrarian for its own sake. It’s building the muscle of personal judgement, strengthening the ability to assess value independently, and developing confidence in solo financial decisions. This shift allows someone to take advantage of genuine matching opportunities when they align with existing values whilst not being dependent on external validation to access generosity or make confident spending choices.
For Singaporeans and Malaysians navigating increasingly sophisticated marketing tactics designed to exploit validation-seeking behaviour, this awareness becomes a practical form of financial protection. The matched donation that genuinely doubles impact? Absolutely worth pursuing. The matched donation that’s the only reason generosity felt possible? That’s worth examining more closely—not to judge the giving, but to understand what it reveals about the relationship with money itself.